From a 20+ Year Oregon Land Specialist Who Reads Every RMLS Report Line by Line Before Advising a Single Client
Every month, RMLS publishes a Market Action Report for Polk and Marion Counties, and every month I read the whole thing — not just the headline numbers, but the price-range breakdown, the area-by-area table, and the fine print in the definitions. The July 2026 report just came out, and it tells a genuinely different story than the same report told a year ago. Inventory is climbing faster than at any point since RMLS started tracking it this way, price growth is real but has slowed to a crawl, and the market is quietly shifting away from the frantic conditions sellers got used to. Here’s what’s actually in the numbers, and what it means whether you’re selling a home, selling bare land, or trying to time a purchase.
I’ve spent more than 20 years selling Oregon bare land, EFU farmland, and timberland, and one habit I’ve never dropped is reading the raw data myself instead of relying on someone else’s summary. Numbers like these drive real decisions — when to list, how to price, whether to wait — so I want you working from the same information I am.
Read more: Is Bare Land a Good Investment in Oregon?
The headline: more homes on the market than buyers can absorb
Active residential listings in Polk and Marion Counties hit 893 in July 2026. That’s not a small increase — it’s up from 764 in July 2025 and 644 in July 2024, a jump of roughly 17% in one year and nearly 39% in two. Look at the shape of that climb below: 2024 and 2025 moved up gradually through the summer selling season. 2026 started higher and kept accelerating.
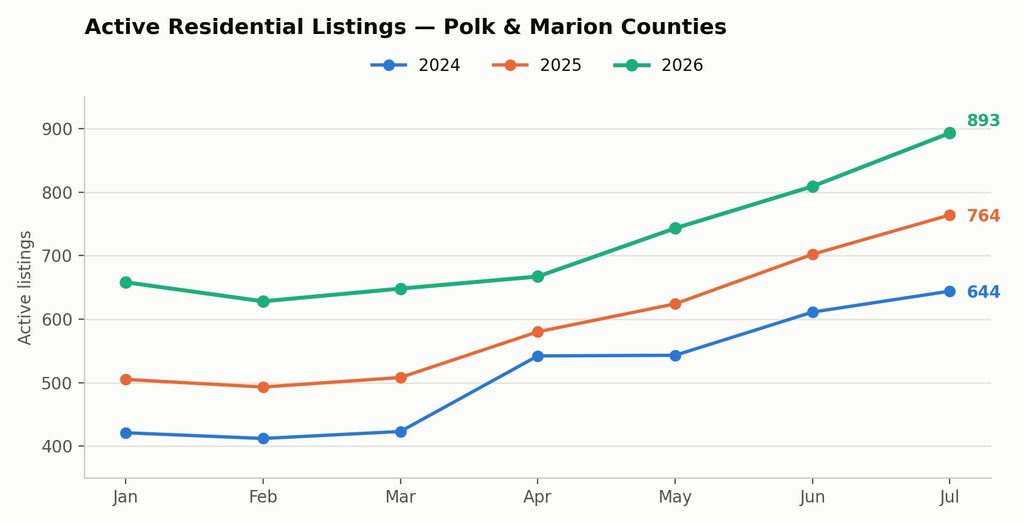
More listings without a matching jump in buyer demand is exactly what pushes a market from a seller’s advantage toward something more balanced — and that’s precisely what the next number shows.
Read more: How Do You Get Water, Power, and Septic on Bare Land in Oregon?
Months of inventory: the real story of 2026
Months of inventory — the number of months it would take to sell everything currently on the market at the current sales pace — is the single best gauge of who has leverage in a negotiation. In July 2026, that number sat at 4.8 months, up from 3.8 in July 2025 and 2.9 in July 2024. January 2026 actually spiked to 5.9 months before settling back down through spring.
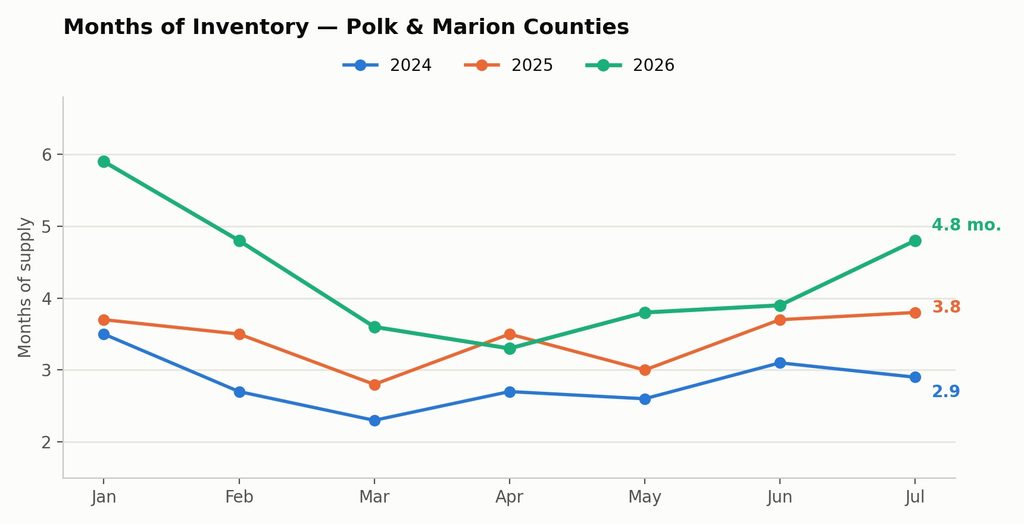
A market is generally consider equal between buyers and sellers somewhere around 5 to 6 months of inventory. We’re not there yet, but 2026 has moved closer to that line than either of the two previous years got at any point. This doesn’t mean sellers have lost the advantage — it means the advantage has narrowed, and pricing a property correctly from day one matters more than it did twelve months ago, when an overpriced listing might still have found a buyer out of sheer competition for scarce inventory.
Read more: Can You Get a Loan to Buy Bare Land in Oregon?
Prices are still rising — just not the way they were
Here’s the part that surprises people who assume more inventory means falling prices: it hasn’t, at least not yet. The average sale price in July 2026 was $484,300, up 4.5% from $463,400 in July 2025. Median sale price was $460,000, up 3.4% from $445,000.
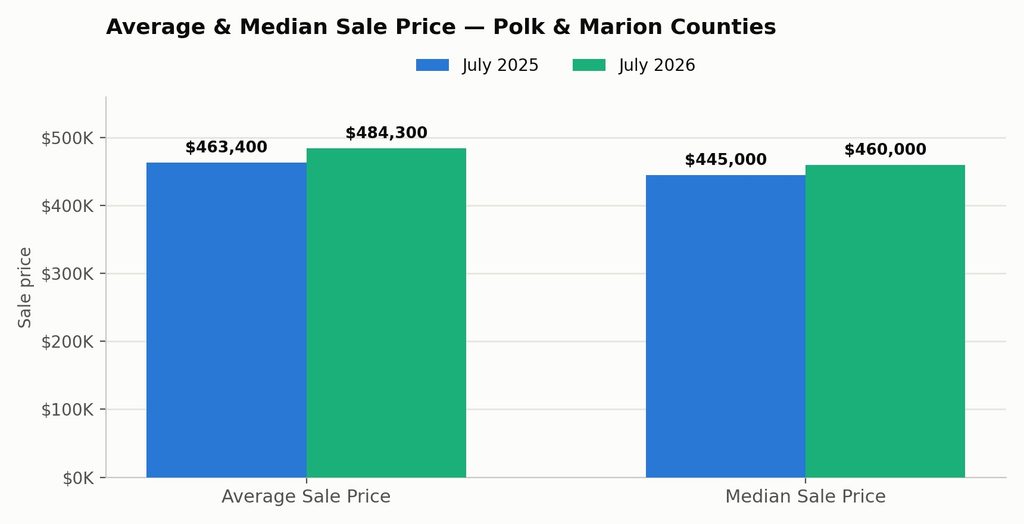
But look at the month-over-month trend instead of year-over-year, and the picture changes: average sale price actually dipped 0.5% from June 2026 to July 2026, even as median price ticked up 3.6% over the same one-month span. Zoom out further and the rolling 12-month numbers tell the calmer version of this story — average sale price is up a modest 2.4% over the trailing year ($480,200 versus $469,000), and median sale price is up just 1.1% ($445,000 versus $440,000). That’s a market still appreciating, but at a pace that looks a lot more like a normal, sustainable year than the sharp run-ups Oregon buyers got used to a few years back.
Read more: What to Check Before Buying Bare Land in Oregon
Where the actual sales are happening
The price-range breakdown in this report is genuinely useful and most people never look at it. In July 2026, the $400,000–$500,000 band accounted for 24.1% of closed sales, up from 21.5% a year earlier — this remains the single busiest price tier in Polk and Marion Counties by a wide margin. The $600,000–$700,000 tier held essentially steady at 19.7%, while the $500,000–$600,000 tier actually cooled, dropping from 32.0% of sales in July 2025 to 23.4% in July 2026. Above $900,000, activity stayed thin but consistent — a handful of sales scattered across the upper brackets, none of it volume, all of it individually meaningful if that’s your price point.
What this tells sellers: the middle of the market, roughly $400,000 to $700,000, is still where the bulk of buyer activity concentrates, and it’s where competitive, well-prepared listings move fastest. Above that range, patience and precise pricing matter even more, because there are simply fewer buyers shopping at once.
New listings, pending sales, and closed sales — a market catching its breath
New listings in July 2026 came in at 363, up 8.7% from July 2025 and up 9.3% from June 2026 — sellers are clearly responding to a market that still supports real prices. But pending sales dropped 8.5% year-over-year to 216, and closed sales fell 6.0% to 187. Put simply: more sellers are testing the market than a year ago, but a smaller share of listings are actually converting to accepted offers and closings at the same pace.
Year-to-date through July, the same pattern holds at a larger scale. New listings for the first seven months of 2026 totaled 2,172, up 5.6% from the same period in 2025. Pending sales, at 1,465, are down just 0.7%, and closed sales, at 1,322, are essentially flat, down 0.2%. This isn’t a market falling apart — it’s a market absorbing more supply at roughly the same closing pace it managed a year ago, which is exactly how inventory numbers climb even while sales hold steady.
Total market time: still fast, but no longer racing
Total market time — the number of days from listing to an accepted offer — was 63 days in July 2026. That’s down 7 days from June’s 70, but up 5 days from July 2025’s 58. Early 2026 saw real volatility here, spiking to over 100 days in March before settling into the 60s by summer. A property that would have gone under contract almost immediately eighteen months ago now has a little more breathing room — which cuts both ways: sellers have slightly less urgency working in their favor, and buyers have a few more days to make a confident decision instead of an impulsive one.
Read more: Can You Build a House on Bare Land in Oregon?
What this means specifically for land sellers
Everything above is residential data, but this same report also tracks land and commercial activity separately, and the numbers are worth knowing if you own bare land, farm ground, or timberland rather than a house. Year-to-date through July, Polk and Marion Counties combined recorded 45 closed land sales at an average price of $397,800. Marion County carried the larger share — 25 closed land sales averaging $412,300 — while Polk County posted 14 closed land sales averaging $365,800. Commercial property, for comparison, saw just 8 closings countywide at a much higher average of $746,600, reflecting how much thinner that market segment is.
Land doesn’t move on exactly the same rhythm as residential inventory, but the same underlying condition — more supply competing for buyer attention — applies just as directly. A rising months-of-inventory number for homes tends to signal a buyer pool that’s being more selective across the board, land included. This is exactly the environment where accurate pricing, a clean title report, and a listing built around a parcel’s real strengths (documented water rights, farm deferral status, usable access, standing timber value) separate a property that sells in a reasonable window from one that sits.
Five things to take from this report if you’re thinking about selling
- Inventory is climbing, but we’re still short of a fully balanced market — sellers retain an edge, just a narrower one than a year ago.
- Price growth has slowed to a healthier, more sustainable pace — don’t price off last year’s rate of appreciation.
- The $400,000–$700,000 range is where the volume is — properties in this band, priced correctly, are still moving with real buyer competition.
- Total market time ticked up year-over-year — build a little more patience into your timeline than you would have eighteen months ago.
- Land sales are tracked separately and behave differently than residential — 45 closed land sales across both counties year-to-date is real, usable context for pricing a parcel, not a home.
Why I read the whole report, not just the summary
Plenty of agents glance at the top-line average price and call it a day. I read the price-range table, the area-by-area breakdown, and the land and commercial columns every single month, because a client selling a $450,000 home in Keizer and a client selling forty acres of EFU ground in unincorporated Marion County are operating in genuinely different micro-markets that happen to share a countywide report. Treating them the same is how sellers get mispriced.
Read more: Oregon Urban Growth Boundary and Land Value: Why Proximity Changes the Number
Frequently asked questions
Does rising inventory mean home prices are about to drop?
Not based on what this report shows — prices are still rising, just more slowly than the sharp increases of recent years. Rising inventory typically shows up as slower price growth and longer market times well before it shows up as falling prices, and that’s exactly the pattern here.
Is this still a good time to sell?
For well-priced properties in the most active range, yes — total market time of 63 days and a still-below-balanced inventory level both favor sellers, just not as dramatically as a year ago. The property that sells fast is the one priced to today’s data, not last year’s.
How is land priced differently from a home in this kind of market?
Land valuation depends far more on specific factors — zoning, water rights, access, timber, lease income — than on the kind of broad comparable-sales approach that drives home pricing, so a rising or cooling residential market matters, but it’s one input among several rather than the whole picture.
Where can I see this data for my specific area within Polk or Marion County?
The full report breaks results down by smaller sub-areas — Woodburn, Keizer, South Salem, and others — and those numbers can vary meaningfully from the countywide averages. I’d rather walk you through your specific area’s numbers directly than have you rely on the countywide figure alone.
Let’s talk about what this means for your specific property
Countywide numbers are a starting point, not a pricing strategy. If you’re weighing whether to list a home, bare land, or farm ground in Polk or Marion County, I’d rather walk you through exactly what these numbers mean for your specific property and area before you make any decision.
About Al Cronemiller — Oregon Land Specialist, MORE Realty, Salem, Oregon. Started working timber with his father at age 12 — cruising timber, running property lines, building logging roads. His grandfather was Oregon State Forester in the 1930s and helped write Oregon’s reforestation bylaws; Cronemiller Lake near Corvallis is named after him. Al spent five years in the City of Salem survey department, owned a construction and remodeling company for 30 years as a licensed general contractor, and worked as a commercial property buyer for institutional hedge fund clients. He holds Land Specialist and Multi-Family Specialist designations and has spent 20+ years selling Oregon bare land, EFU farmland, timberland, and investment property.
This is Al Cronemiller, your Salem Oregon Bare Land Specialist. I always answer.
503-949-5025 | al@cronemiller.com | HomesForSaleSalemOregon.net
This article is educational and general in nature and reflects data published by RMLS for the July 2026 reporting period. Market data changes monthly — talk with Al directly about current conditions for your specific property and area.